donderdag 4 februari 2016

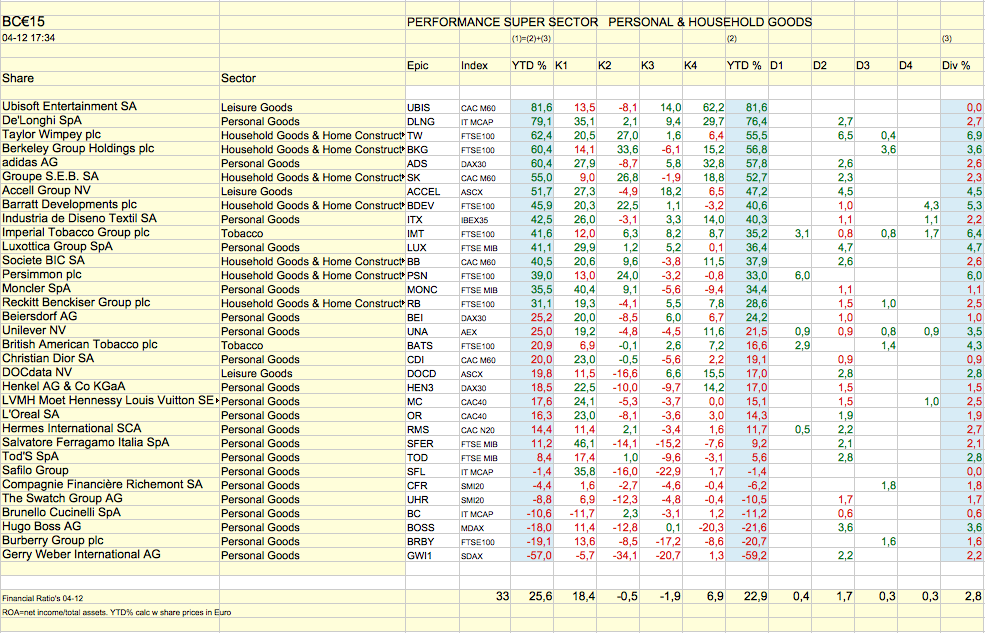
De'Longhi SpA FY 2015 Return on Assets increased to 14.8 (2014 : 12.2)

Financial Ratio's De'Longhi SpA 


Source : EuropeanMarkets

CEO Fabio de’ Longhi said “The performance achieved in 2015 witnesses the De’Longhi Group’s capacity to continue along its growth path, despite a highly competitive market and a materially adverse foreign exchange scenario. However, we do not expect that these unfavorable developments experienced throughout the year will be such to prevent the Group from achieving its targets on margins and cash generation, thanks to the commercial and organizational initiatives put in place by the Company”.

The De’Longhi Group’s 2015 consolidated revenues reached about € 1,891 million, up by about 9.5% (about +6.6% at constant exchange rates). During Q4 2015, the Group’s revenues totaled about € 676 million, approximately a +5.6% increase, or about +3.9% at constant exchange rates, compared to Q4 2014, which experienced a very sustained organic growth, partly linked to very favorable market conditions (such as very high sales in Russia, in anticipation of material price increases due to the Ruble’s devaluation).
Analyzing FY 2015 revenues by market, it is worth highlighting that all the Group’s geographical areas recorded a good growth, with the only exception of North East Europe, where revenues’ growth was more limited.

More in detail, Europe ended the 12 months with a +7.1% growth, led by South West Europe (up by about +9.8%, with strong performance in Italy, Austria, Iberia and Switzerland), while in the North East Europe area growth (up by some +2.9%) in markets such as Poland, Hungary, Czech Republic and Scandinavia was partially offset by an unfavorable performance in Russia and Ukraine, negatively affected also by a sharp devaluation of the local currencies.
The APA area (Asia-Pacific-Americas) revenues recorded a sustained growth, increasing by about +17.1%, also thanks to a positive foreign exchange contribution: among the markets that contributed the most to the overall performance we highlight North America, South Korea, Australia, China and Brazil.

The MEIA division (Middle East, India, Africa) ended FY 2015 with a revenues’ increase of about +10.1%, thanks to a particularly favorable foreign exchange impact: revenues at constant exchange rates suffered from the impact of the political and military crisis that affected part of the Middle-East area.


Source :  Press Release De'Longhi, Treviso (Italy), January 25, 2016

woensdag 3 februari 2016

ams AG FY 2015 Return on Assets higher to 12.0 (2014 : 11.0)

Financial Ratio's ams AG


source : EuropeanMarkets


ams AG a leading worldwide manufacturer of high performance sensor and analog solutions, reports record full year results for 2015 showing strong year-on-year growth in revenues and earnings. The success of ams’ consumer solutions for smartphones and mobile devices was the key factor driving ams’ positive business performance last year. For the first quarter 2016, ams expects softer end market demand in its consumer business and typical seasonal effects to result in sequentially lower expected revenues of EUR 131-138 mil­lion.

2015 full year revenues grew 34% to EUR 623.1 million (USD 691.4 million), at the same time gross margin was unchanged at 56% (excluding acquisition-related amortization). The full year operating (EBIT) margin increased to 26% (excluding acquisition-related amortization). Revenues for the fourth quarter 2015 were EUR 147.2 million, up 6% year-on-year and down 4% quarter-on-quarter. Gross margin for the fourth quarter 2015 stood at 57% (excluding acquisition-related amortization), up from 56% last year, while the operating (EBIT) margin reached 23% (excluding acquisition-related amortization).

Based on the company’s cash dividend policy stipulating the distribution of 25% of net earnings, ams will propose a dividend of EUR 0.51 per outstanding share for 2015.

Outlook

Based on currently available information, ams expects its business to develop positively and record further growth in the current year.

For the first quarter 2016, ams expects softer end market demand, particularly in its smartphone business, and typical seasonal effects to result in sequentially lower expected revenues of EUR 131-138 million.

Despite this development ams anticipates first quarter gross margin to remain on a comparable level to the fourth quarter 2015. Given the end market-driven revenue outlook, seasonal effects and continued R&D investments for growth, ams expects first quarter operating margin (excluding acquisition-related amortization) in a range of 18-20%. 
source : Press Release ams AG, Premstaetten, Austria, February 2, 2016

Continental AG FY 2015 Return on Assets increased to 13.1 (2014 :11.1)

Financial Ratio's Continental AG 


Source : EuropeanMarkets

“In 2015, we continued to generate profitable growth in a generally challenging environment. Market growth in Europe and the U.S.A. helped us to compensate for slower growth in China, major recessions in Russia and Brazil, and the decline in industrial business, particularly in the raw materials sector. Once again, we could rely on the hard work demonstrated by our employees around the world, who now number more than 208,000,” said Continental Executive Board chairman Dr. Elmar Degenhart on Monday at the announcement of the preliminary key data during   the North American International Auto Show in Detroit, Michigan, U.S.A.

“In 2016, we expect global production of passenger cars and light commercial vehicles with a total weight of up to six tons to increase slightly from around 88 million vehicles to 89 million. We anticipate a sales increase of around 5 percent to approximately €41 billion. We aim to maintain our adjusted EBIT margin again at more than 10.5 percent,” Degenhart added.

Continental will present its preliminary business figures on March 3, 2016, at another digital-only financial press conference.


Source :  Press Release Continental AG, Hannover (Germany), January 11, 2016

Moët Hennessy Louis Vuitton FY 2015 Return on Assets higher to 11.1 (2014 : 10.2)

Financial Ratio's Moët Hennessy Louis Vuitton LVMH


source : EuropeanMarkets


CEO Statement

Bernard Arnault, Chairman and CEO of LVMH, said: “The 2015 results confirm the capacity for LVMH to progress and gain market share despite economic and geopolitical uncertainty. Revenue and operating profit reached new record levels. Commitment to excellence, a passion for quality and our capacity to innovate underpin our growth momentum and are all values epitomised by the Fondation Louis Vuitton and its emblematic building that welcomed over one million visitors in 2015. All our Maisons demonstrated outstanding flexibility in 2015. By adapting their strategies to global changes and by continuing to evolve, they have shown the creativity and entrepreneurship that drive them forward. In an uncertain economic environment, we can rely on the desirability of our brands and the agility of our teams to further strengthen in 2016 our leadership in the world of high quality products.”
Outlook

Despite a climate of economic, currency and geopolitical uncertainties, LVMH is well-equipped to continue its growth momentum across all business groups in 2016. The Group will maintain a strategy focused on developing its brands by continuing to build on strong innovation and a constant quest for quality in their products and their distribution.

Driven by the agility of its teams, their entrepreneurial spirit, the balance of its different businesses and geographic diversity, LVMH enters 2016 with confidence and has, once again, set an objective of increasing its global leadership position in luxury goods.


Dividend increase of 11%

At the Annual Shareholders’ Meeting on April 14, 2016, LVMH will propose a dividend of €3.55 per share, an increase of 11%. An interim dividend of €1.35 per share was paid on December 3 of last year. The balance of €2.20 per share will be paid on April 21, 2016.

source : Press Release Moët Hennessy Louis Vuitton, Paris, February 2, 2016

dinsdag 2 februari 2016

ASML Holding NV FY 2015 Return on Assets higher to 12.8 (2014 : 11.7)

Financial Ratio's ASML Holding NV


source : EuropeanMarkets


CEO Statement
"Our full-year 2015 net sales marked a new record at EUR 6.3 billion, up from EUR 5.9 billion in 2014, including service and field option sales that rose to a record EUR 2 billion. We expect 2016 first-quarter sales at approximately EUR 1.3 billion. As we indicated three months ago, we expect our logic customers to take shipments of our leading edge immersion tools in the second quarter in preparation of their 10 nanometer node ramp. As a result, we expect second-quarter sales to increase significantly from the first-quarter level," ASML President and Chief Executive Officer Peter Wennink said. 

Outlook
For the first-quarter of 2016, ASML expects net sales at approximately EUR 1.3 billion, a gross margin of around 42%, R&D costs of about EUR 275 million, other income of about EUR 23 million -- which consists of contributions from participants of the Customer Co-Investment Program --, SG&A costs of about EUR 90 million and an effective annualized tax rate of around 13%.
source : Press Release ASML Holding NV, January 20 2016

dinsdag 1 december 2015

Atlas Copco Group FY 2015 Return on Assets higher to 18.7 (2014 : 16.2)

Financiële Ratio's Atlas Copco Group


Source : EuropeanMarkets

Summary of nine-month results

Orders received in the first nine months of 2015 increased by 10% to MSEK 76 394 (69 498), corresponding to a 3% organic decline. Structural changes added 2%, and the currency effect was +11%. Revenues were MSEK 76 579 (68 361), corresponding to a 2% organic decline.

Operating profit was MSEK 14 904 (12 244). The operating margin was 19.5% (17.9). The positive impact of changes in exchange rates was to MSEK 2 680.
Profit before tax was MSEK 14 179 (11 655), corresponding to a margin of 18.5% (17.0). Profit for the period totaled MSEK 10 693 (8 840). Basic and diluted earnings per share were SEK 8.78 (7.27) and 8.72 (7.27) respectively.

Operating cash flow before acquisitions, divestments and dividends totaled MSEK 11 600 (9 040).

Near-term demand outlook

The overall demand for the Group is expected to remain at current level.


Source : Atlas Copco Group Third-quarter report 2015, Stockholm (Sweden) 20 October 2015

Alfa Laval AB FY 2015 Return on Assets higher to 10.9 (2014 : 8.4)


Financiële Ratio's Alfa Laval AB


Source : EuropeanMarkets

Comment from Lars Renström, President and CEO

“Net sales and result reached record levels for a third quarter. At the same time strong cash flows contributed to a reduction of the net debt in relation to EBITDA to below 1.8. The order intake was 8.7 billion – a sequential downturn of 5 percent, mainly explained by fewer large orders being booked.
Within Process Technology the order intake increased somewhat, thanks to the Food & Life Science segment. Demand from the oil and gas sector was on the whole slightly higher than the previous quarter, with good growth in the mid- stream business and petrochemicals. Marine & Diesel showed a sequential downturn, reflecting lower demand for new equipment.
A favourable mix of ship contracts dampened the downturn. Service showed growth, with a particularly good development within pumping systems. Within the Equipment division the order intake decreased sequentially, partly due to vacation effects and a large non-recurring order, partly due to lower demand within Sanitary.
Asia showed a positive development. The market in China grew somewhat, where especially the food related demand developed well. The U.S. showed a decline, primarily explained by larger orders not being repeated. The oil and gas related business was unchanged compared to the previous quarter.”

Financial highlights first nine months of 2015

Order intake decreased by 2 percent* to SEK 27,676 (26,151) million.
Net sales increased by 11 percent* to SEK 28,941 (24,292) million. 
Adjusted EBITA was SEK 5,065 (3,955) million.
Adjusted EBITA margin was 17.5 (16.3) percent.
Result after financial items was SEK 4,059 (2,944) million. 
Net income was SEK 2,926 (2,057) million.                                         
Earnings per share was SEK 6.93 (4.88).
Cash flow from operating activities was SEK 3,975 (3,433) million.
Impact on EBITA of foreign exchange effects was SEK 370 (-27) million.
Impact on result after financial items of comparison distortion items was SEK - (-320) million.

* Excluding currency effects.


Outlook for the fourth quarter

“We expect that demand during the fourth quarter 2015 will be in line with or somewhat higher than in the third quarter.”

Source : Press Release Alfa Laval AB, Lund (Sweden) 27 October 2015

maandag 30 november 2015

Assa Abloy AB FY 2015 Return on Assets higher to 12.3 (2014 : 10.6)


Financiële Ratio's Assa Abloy AB


Source : EuropeanMarkets

Comments by the President and CEO

“The third quarter and the first nine months continued very strongly for ASSA ABLOY, with a rise in sales of 19% for the quarter and totaling 21% for the first nine months of the year,” says Johan Molin, President and CEO. “Operating income grew very satisfactorily by a full 19% for the quarter and a total of 22% for the 9-month period.
“Organic growth for the quarter was 3%, with the mature markets in the USA, the Pacific and Europe continuing their strong growth. However, Global Technologies showed a weak development during the quarter because of delayed projects on the Government ID side and in Biometry. In Asia, the market downturn in China continued at the same time as other markets in the region showed strong growth.
“ASSA ABLOY’s leadership in the field of innovation was recognized once again at ASIS, the USA’s largest security exhibition, where four first prizes were won for innovation. The areas where ASSA ABLOY has been particularly successful include physical access and identity; energy-efficient locks; electromechanical locks; and on-line connected digital door locks for the private residential market. All these areas have great potential for the future, with energy-efficient solutions advancing especially strongly.
“Nergeco, which is the market leader in high-speed doors in the French market and with a strong position in southern Europe in general, was acquired during the quarter. Some further minor acquisitions were made during the quarter. One company acquired was Pickersgill Kaye in the UK, which complements the Group in the high-security lock segment.
“Operating income rose by a full 19% during the quarter. The organic growth of 3% resulted in a good underlying growth in the operating margin, to which continued efficiency improvements contributed especially strongly. However, the margin was unchanged this quarter, being affected by negative exchange-rate effects as well as the normal dilution due to acquisitions.
“My judgment is that the global economic trend remains weak. Although America is showing a positive trend, Europe and many of the Emerging Markets are stagnating. However, our strategy of expanding on the Emerging Markets remains unchanged, since in the long term they are expected to achieve very good economic growth. We are also continuing our investments in new products, especially in the growth area of electromechanics.”

First nine months of the year

Sales for the part-year period totaled SEK 49,799 M (40,996), representing an increase of 21%. Organic growth was 4% (3). Acquired units contributed 3% (10). Exchange-rate effects had a positive impact of SEK 5,561 M on sales, that is 14% (3), compared with the corresponding period of 2014. Operating income before depreciation and amortization, EBITDA, for the part-year period amounted to SEK 9,106 M (7,430). The corresponding margin was 18.3% (18.1). The Group’s operating income, EBIT, amounted to SEK 8,041 M (6,575), which was an increase of 22%. The corresponding EBIT operating margin was 16.1% (16.0).
Earnings per share for the part-year period amounted to SEK 5.02 (4.09), a rise of 23%. Operating cash flow totaled SEK 5,327 M (4,769).

Long-term outlook

Long term, ASSA ABLOY expects an increase in security-driven demand. Focus on end-user value and innovation as well as leverage on ASSA ABLOY's strong position will accelerate growth and increase profitability.

Organic sales growth is expected to continue at a good rate. The operating margin (EBIT) and operating cash flow are expected to develop well.

Source : Press Release Assa Abloy AB, Stockholm (Sweden) 20 October 2015

SKF B FY 2015 Return on Assets lower to 9.3 (2014 : 9.6)


Financiële Ratio's SKF B


Source : EuropeanMarkets

Alrik Danielson, President and CEO:

“The expected weakening of market demand that we flagged for in July materialised and gathered pace during the quarter, especially in Asia and North America. As a result, sales in local currency declined by 5%. Production rates were reduced during the quarter and inventories were kept under control. Our financial performance was impacted by the lower sales volumes.

Agreements have been reached with almost all of the 1 500 white-collar staff that is part of our cost reduction programme. Given current market conditions, these actions alone are, however, not sufficient and we will continue our cost reduction activities across the Group.

In Europe, we saw growth in the railway sector but significantly weaker demand in both the energy and metals sectors. In North America and Asia, overall industrial demand was significantly lower, with the exception of the energy sector in Asia, which saw significant growth.

Our automotive business grew in line with overall market development in Europe but not in North America.

The Automotive Market profit improvement programme is progressing, with a more detailed update to be presented at our upcoming Capital Markets Day.

Divestments of non-core businesses continued, with the sale of Canfield Technologies. The proceeds are being used to strengthen the balance sheet and to be reinvested in our core business.

Entering the fourth quarter, we expect the macro-economic uncertainty to continue and as a consequence we expect demand in the fourth quarter to be slightly lower sequentially and lower year-over-year. We are adjusting our production levels accordingly.”

Outlook for the fourth quarter 2015

Demand compared to the fourth quarter 2014
The demand for SKF’s products and services is expected to be lower for the Group where demand for the Auto motive Market is expected to be relatively unchanged, while demand for the Specialty Business is expected to be slightly lower and demand for the Industrial Market is expected to be lower. Split by markets, demand is expected to be relatively unchanged in Europe and Latin America and significantly lower in North America and Asia.

Demand compared to the third quarter 2015

The demand for SKF’s products and services is expected to be slightly lower for the Group where demand for the Industrial Market and the Automotive Market is expected to be slightly lower while demand for the Specialty Business is expected to be relatively unchanged. Split by markets, demand is expected to be relatively unchanged in Europe and slightly lower in North America, Latin America and Asia.


Source : Press Release SKF B Nine-month report 2015, Gothenburg (Sweden) 16 October 2015

Grifols SA FY 2015 Return on Assets slightly higher to 10.3 (2014 : 10.2)

Financial Ratio's Grifols SA


Source : EuropeanMarkets

Financial highlights

Grifols’ EBITDA to September 2015 reached Euros 856.8 million, a rise of +11.3% compared to the figure of Euros 769.8 million reported for the same period of 2014.
The EBITDA margin reached 29.8% of revenue. Margins were primarily affected by the competitive intravenous immunoglobulin market in the United States, that has not deteriorated during the third quarter; by the decrease of royalties income from the transfusion diagnostics unit; and by the simultaneous operation of two fractionation plants at Clayton (North Carolina, United States) while all production is gradually transferred to the new plant.

The geographic mix of revenues and a slight increase in the cost of plasma related to the opening of new plasma collection centers have been offset by the improvement in production and operational efficiencies obtained in the group's plants.
To September 2015, EBIT has risen by +13.7% to Euros 718.0 million, a figure that represents 25.0% of revenue.
Financial expenditure has declined by -2.3%, or -16.5% when exchange rate effects are excluded.

The net profit attributable to the group has risen by +18.5% to the third quarter and reached Euros 401.6 million, representing 14.0% of revenue.

Source : Financial Results Grifols, Barcelona (Spain), November 4, 2015

Técnicas Reunidas SA FY 2015 Return on Assets slightly higher to 6.7 (2014 : 6.5)


Financiële Ratio's Técnicas Reunidas SA


Source : EuropeanMarkets

Financial highlights

• At the end of September 2015, Tecnicas Reunidas’ backlog reached a new high of € 9,977 million, 14%, higher than the 9M 2014, due to a strong order intake. The main contract added to the order book during the 3Q 2015 was the Al Zour refinery project for KNPC in Kuwait.
• After the end of the third quarter, the company signed its first engineering and procurement contract (EP) for Sasol in the US and the ADOC upstream project in Abu Dhabi, to be included in the 4Q 2015 backlog.
• In 9M 2015, revenues grew by 31% to € 3,006 million, as a result of the backlog execution.
• Following sales growth, EBITDA and EBIT grew by 27.0% respectively, to € 159 million and € 148 million. In the 9M 2015, operating margins were slightly lower than the year before.
• Net profit went up 16% to € 115 million, despite a higher tax rate and a smaller financial income.
• Net cash position decreased to € 348 million at the end of September 2015. This is due to the combination of lower downpayments in the recent awarded projects and longer payment milestones in certain large projects under execution.

Outlook

Oil price "lower for longer"
Capex reduction depending on clients and geographies
Clients adapting to oil price scenario's
- longer payment terms
- efficiency plans

Source : 9M 2015 Financial Results Técnicas Reunidas SA, 16th of November 2015

MARR SpA FY 2015 Return on Assets lower to 8.1 (2014 : 10.7)


Financiële Ratio's Marr SpA


Source : EuropeanMarkets


At the end of third quarter the increase in revenues and profits in the first nine months of the year confirmed:

Total consolidated revenues of 1,152.7 million Euros (1,118.1 in 2014)
Consolidated EBITDA of 88.0 million Euros (84.6 in 2014)
Consolidated EBIT of 75.5 million Euros (72.6 in 2014)
​Net consolidated result of 48.9 million Euros (43.6 in 2014) benefitting from a non-recurrent income of 1.7 million

Outlook

In a market context which in the last few months has shown a gradual improvement, also benefitting from favourable conditions such as the EXPO event and the good performance during the summer season, on the basis of the results of the first nine months, the management team confirms its objectives for the end of the business year: increase in market share, maintaining the profit levels achieved and keeping the absorption of the net trade working capital under control.


Source : Press Release Marr SpA, Rimini (Italy), 13 November 2015